Why I Generally Recommend Private Term Life Insurance Over NYSUT
If you're a New York teacher, you've probably seen the life insurance offered through NYSUT Member Benefits. While convenient, I generally recommend comparing it with an individually owned term life insurance policy.
My biggest concern is the cost of maintaining coverage as you get older.
What does $1 million in life insurance cost?
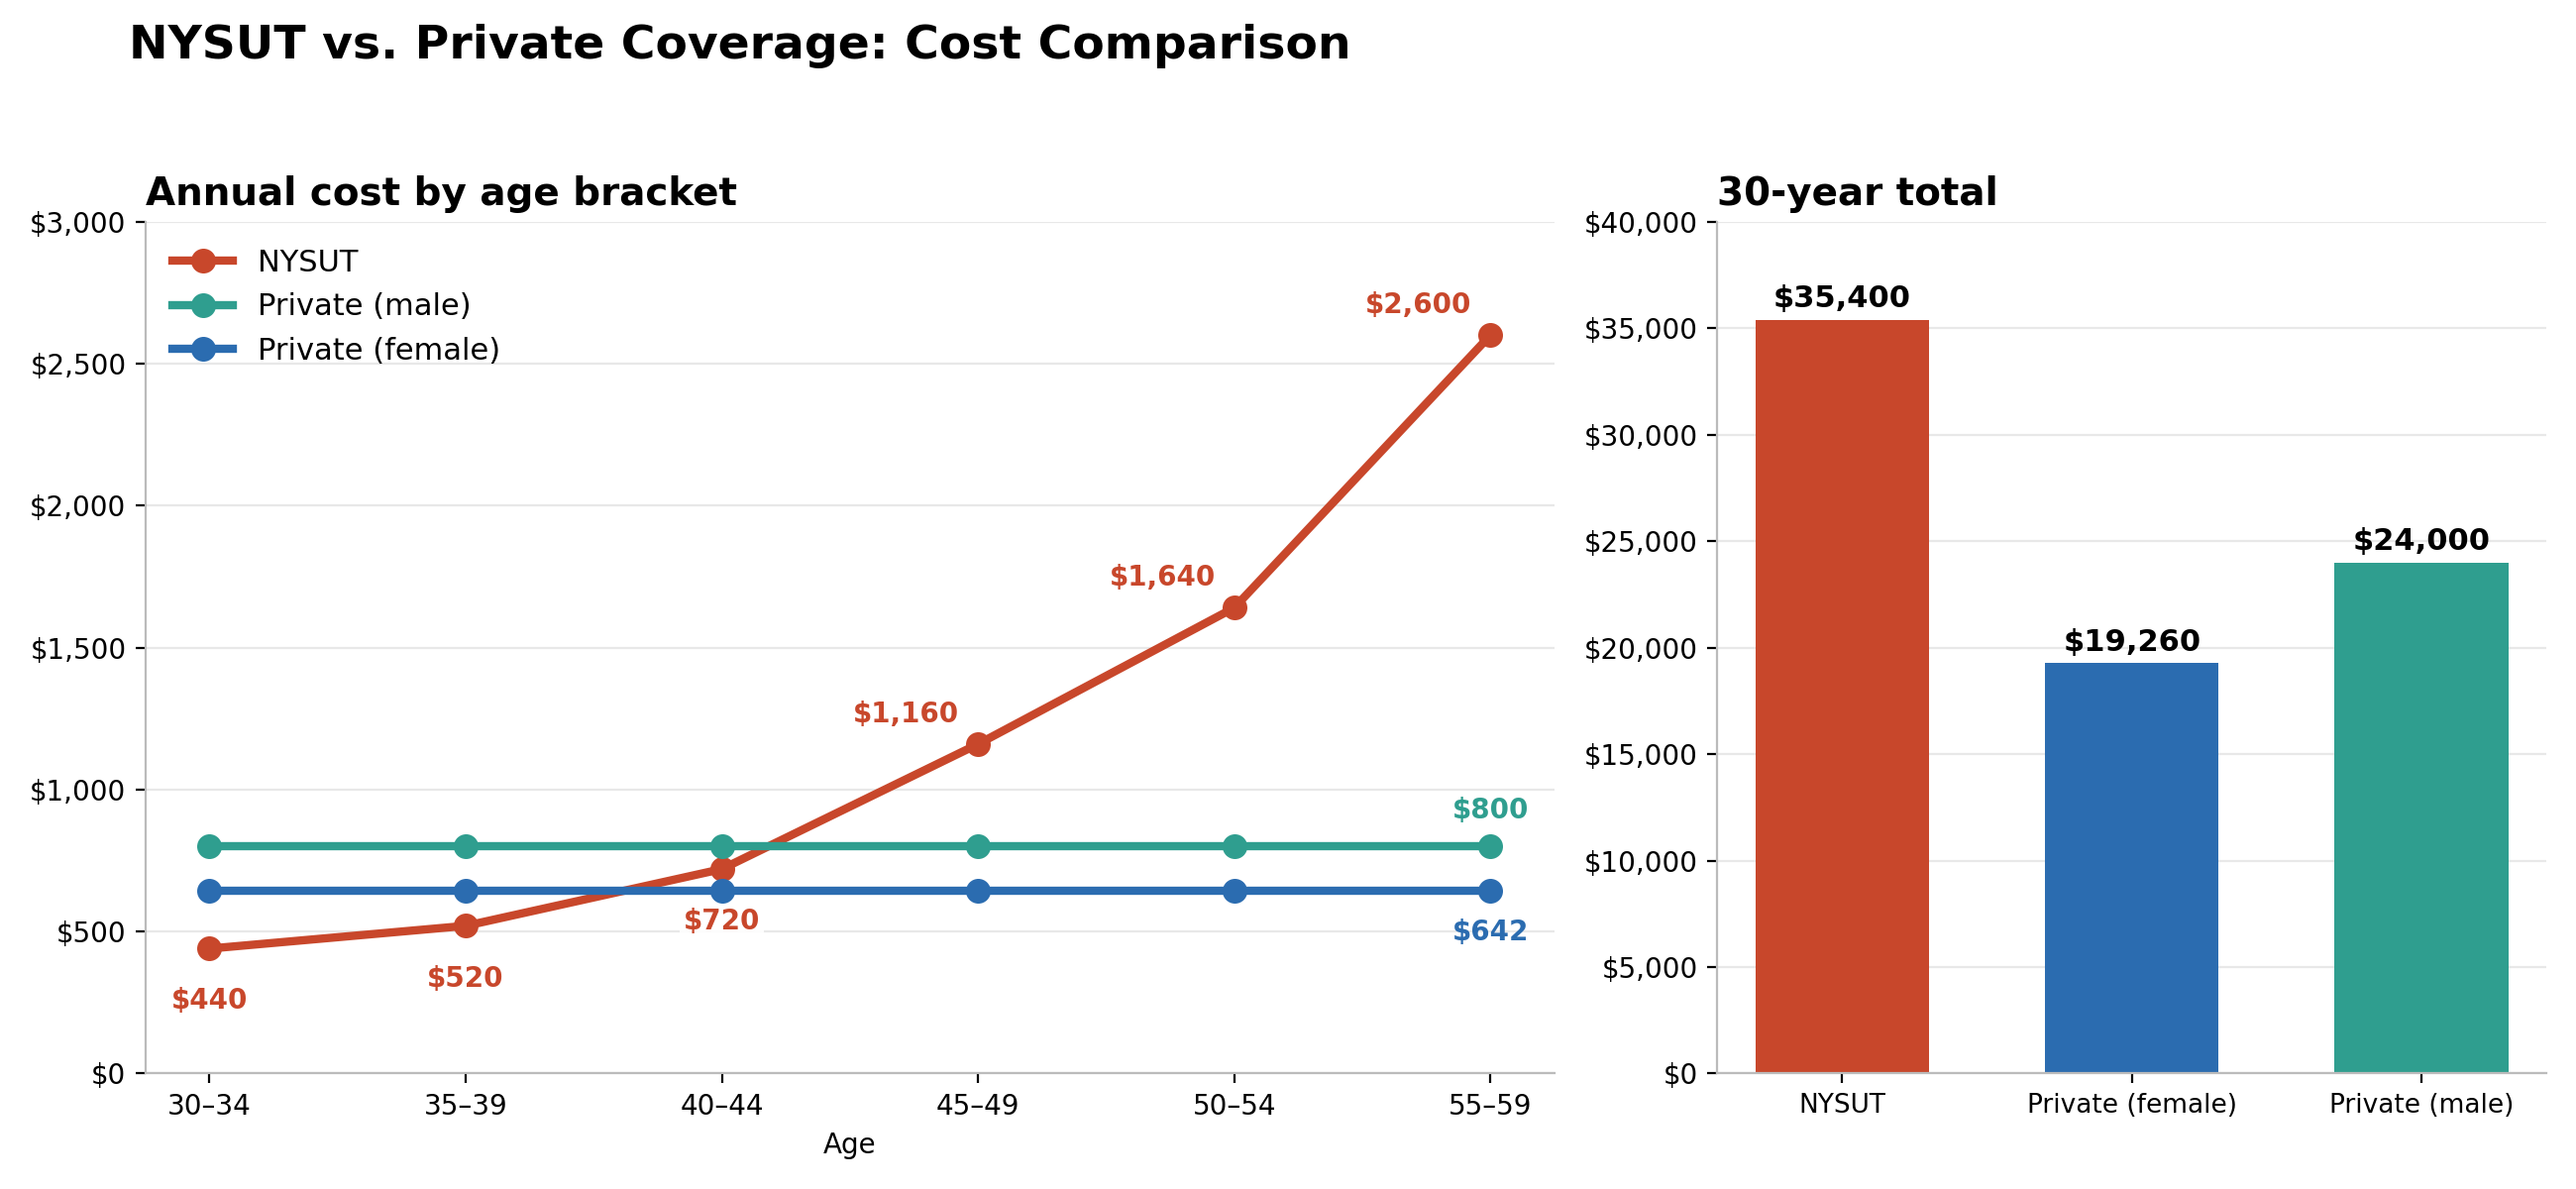
Let's look at a 30-year-old teacher who wants $1 million of life insurance coverage until age 60.
Using NYSUT's published age-based rates and illustrative private term insurance premiums for applicants in Preferred health classes, here's how the costs compare:
Estimates assume the listed rates remain unchanged. Private premiums assume a 30-year level-term policy with a fixed annual premium. Actual premiums depend on underwriting, eligibility, and insurer. Verify all rates and plan provisions before publishing.
Why I generally prefer private term insurance
When you're working, life insurance is primarily about protecting your family if something happens to you before your financial goals are met.
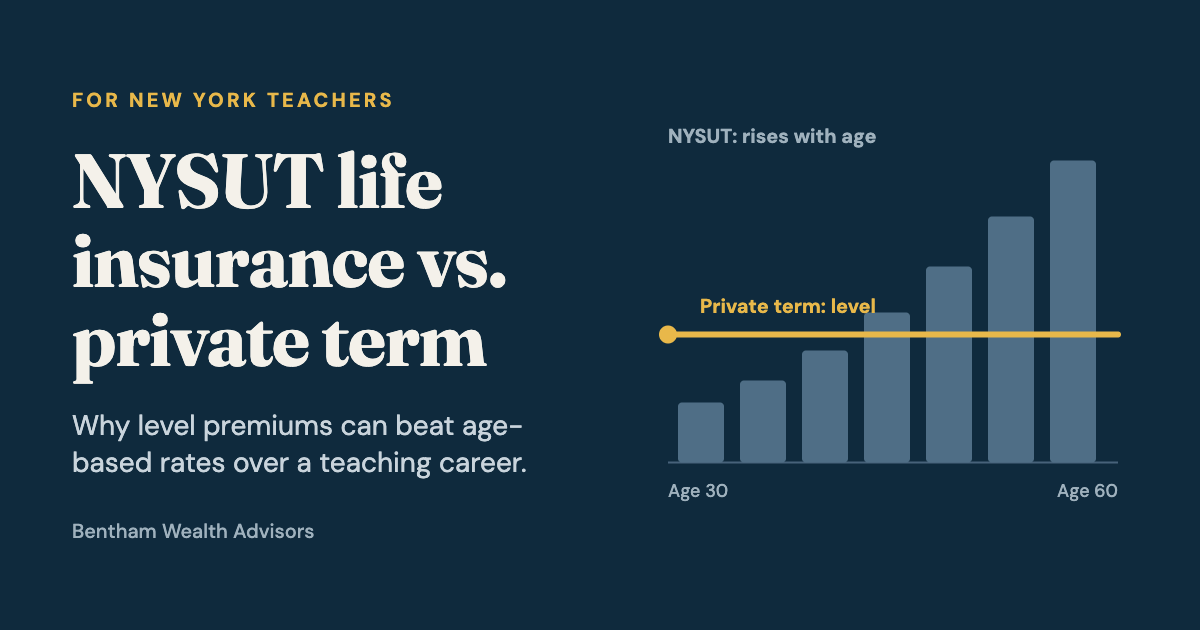
An individually owned 30-year level-term policy can provide a consistent $1 million death benefit with premiums that stay level for the full term. By comparison, NYSUT's standard term plan uses age-based premium rates that increase as you get older.
For teachers who qualify for competitive rates, private term insurance can offer predictable costs and coverage designed around their working years.
Two Reasons Why NYSUT life insurance might make sense
Although I generally prefer private term insurance, there are situations where NYSUT coverage may be worth considering.
1. You only need coverage for a short period.
Many individual term policies have minimum term lengths of 10 years. If you're retiring in five or seven years a shorter-duration option through NYSUT may be worth exploring. Compare the available NYSUT options and their actual terms before deciding.
2. You have health issues.
Individual life insurance underwriting can be strict. Certain medical conditions, medications, or health histories may lead to higher premiums or a declined application. Depending on the NYSUT plan's eligibility and underwriting requirements, its coverage could be a useful alternative. Don't assume acceptance is guaranteed—review the actual requirements.
My recommendation for New York teachers
Don't automatically enroll in life insurance through your union without comparing the alternatives.
Start by determining how much coverage your family needs and how long you'll need it. Then compare NYSUT's available options with individual term policies, including the premiums, guaranteed benefit, underwriting requirements, and renewal provisions.
For many healthy teachers who need coverage for 10 to 30 years, I would start by evaluating an individually owned level-term policy. But if you need coverage for a shorter period or have health issues that make individual insurance difficult to obtain, NYSUT may deserve a closer look.The goal is to find the coverage that best protects your family’s needs at the most competitive price—not simply to choose the most convenient option.
The goal is to get the right coverage for your family at the best price.
This article is for educational purposes only and is not individualized insurance advice. Verify current rates and policy provisions before making a decision. Never cancel existing coverage until replacement insurance is approved and in force.